If you’re 52 with $2 million invested, a 30% market drop isn’t just a $600,000 loss.
It could mean working another three to five years.
You can recover money. But you can't recover time.
$2M+ INVESTED • RETIREMENT STARTING TO FEEL REAL
THE PROBLEM HAS CHANGED
The strategy that built your wealth may need to evolve.
For most of your career, the playbook was simple:
save, invest, ride out volatility, and give the market time.
But once retirement is within sight, time becomes part of the risk equation.
$2.0M
Initial Portfolio
→
$1.4M
After 30% decline
What happens to retirement?
Most investors feel stuck between two bad choices.
Stay Aggressive
• More growth potential
• Larger potential drawdowns
• Retirement timing risk
Get Conservative
• Smaller expected swings
• Less growth potential
• Inflation + longevity risk
But what if there is a third option?
A DYNAMIC APPROACH
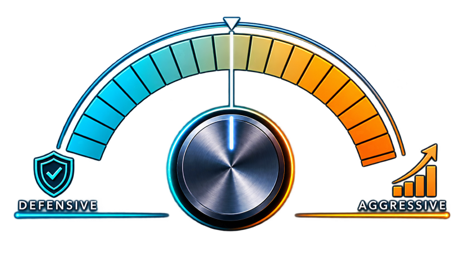
Risk doesn’t have to be static.
Your portfolio doesn’t have to take the exact same amount of risk in every environment.
1. READ THE ENVIRONMENT
Growth • Inflation • Interest Rates
2. FOLLOW MARKET EVIDENCE
Trend • Momentum • Market Structure
3. ADJUST THE RISK DIAL
Ranges • Position Sizing • Gradual Shifts
Probabilities, not predictions.
Not all-in / all-out. Not trying to call every top or bottom.
WHO THIS IS BUILT FOR
$1M+ INVESTED
Approaching Retirement
Is this where you are now?
✔ Architect or engineer between 45-60
✔ Retirement is becoming real, not theoretical
✔ You've mostly been letting your investments ride
✔ You still want meaningful long-term growth
✔ A major drawdown could materially affect your plans
✔ You don't want your risk dictated only by your age
See How the Dynamic Investing Strategy Works
Access the full video below explaining the framework, risk dial, and decision process.
DISCLAIMER:
Not investment advice. Information provided for general education purposes only. Past performance is not a guarantee of future results.